Homeowners in Decatur and Athens can avoid paying a roofing bill at once by combining an accurate roof quote with payment-plan options. Huntsville Roofing Solutions has publicly described third-party financing options that may include $0-down structures, fixed monthly payments, promotional plans, and repayment terms of 120 or 180 months. Those published examples do not confirm that any particular plan is currently approved or available; actual options depend on the financing provider, the applicant, and the lender agreement. Before choosing a plan, confirm whether the roof needs repair or replacement, check any legitimate storm-related insurance coverage, and compare total repayment—not only the monthly amount. Decatur and Athens homeowners can request inspections, review the project cost, and choose the payment approach that fits best.
This guide focuses specifically on how homeowners in Decatur and Athens can think through the payment side of a roofing project after the roof has been inspected and priced. It does not replace the local roofing pages or the main financing resources on the site.
The most useful sequence is simple: determine what the roof actually needs, get the project price in writing, check whether legitimate insurance coverage applies, decide how much you want to pay directly, and then compare financing for any remaining balance.
Are Roof Payment Options Available for Both Decatur and Athens Homeowners?
Huntsville Roofing Solutions serves both Decatur and Athens as part of its broader North Alabama service area. The financing information on the site is therefore not limited to homeowners inside Huntsville itself.
The city where the property is located is usually less important to the financing decision than the actual project amount, the amount being financed, lender approval, creditworthiness, repayment term, and promotional conditions.
If you are still researching the roofing work itself, use the dedicated Decatur roofing contractors page or the Athens roofing contractors page.
Those pages cover local roofing services and service-area information. This guide focuses on what happens after you know what work your roof needs and how much that work will cost.
What Types of Roof Payment Plans Can Homeowners Compare?
The company’s publicly posted financing information has described third-party lending options that may include $0-down structures, longer-term monthly payments, deferred-interest promotions, and payment deferral options. Individual programs and terms must be verified with the financing provider.
Programs, rates, terms, and approval requirements can change. Use the roof financing page to learn about advertised options, then confirm current availability, required disclosures, and the actual offer directly with the financing provider. A website article is not an approved lender rate sheet.
$0-Down Financing Structures
A $0-down structure can reduce the amount of cash required at the beginning of an approved roofing project. Instead of making a large upfront payment, the approved amount is repaid according to the lender agreement.
However, “$0 down” describes the payment structure. It does not mean that every homeowner will qualify, and it does not mean that borrowing is free.
Longer-Term Monthly Payment Plans
Longer repayment terms can reduce the required monthly payment because the financed amount is spread across more months. The company’s published materials have referenced both 120-month (10-year) and 180-month (15-year) financing examples. The 180-month term is the longer of those advertised examples, not a currently verified offer.
The tradeoff is important: a lower monthly payment can result in a higher total repayment when interest is charged for a longer period.
Deferred-Interest Promotional Plans
Some promotional financing structures may waive accrued interest when the promotional balance is paid completely within the required period.
These plans should not automatically be treated as ordinary interest-free loans. Under a deferred-interest structure, interest may accrue from the purchase date. If the required balance is not fully paid by the promotional deadline, accrued interest may become payable according to the lender agreement.
Deferred-Payment Options
Some plans can delay when required payments begin. That can be useful when a roof needs immediate attention but a homeowner expects their financial situation to change later.
However, “no payments” does not necessarily mean that interest is not accruing during the deferral period. Always review the actual lender terms.
What Could a Monthly Roof Payment Look Like?
The monthly amount depends on three primary variables: how much you finance, the approved interest rate, and the repayment term.
For a mathematical illustration, consider a $15,000 roofing project financed at an assumed 7.99% fixed APR over 180 months, with no additional financed fees. The rate and term have appeared in the company’s published financing materials, but this example is not a current financing offer or confirmation of lender approval.
Using standard monthly amortization and rounding the payment to cents, the example works out to approximately $143.26 per month for 180 months, or about $25,787 in total payments, including about $10,787 in interest. Exact totals may vary slightly because of rounding and any terms or fees in an actual agreement.
This hypothetical example illustrates why homeowners should not compare financing by monthly payment alone. A specific loan offer must be evaluated using the lender’s approved APR, amount financed, repayment schedule, and full disclosures.
When reviewing an offer, compare:
- The amount being financed
- The approved interest rate or promotional structure
- The monthly payment
- The number of payments
- The total finance charge
- The total amount repaid
A smaller monthly payment may be easier on the household budget, but a longer repayment period can increase the total cost of borrowing.
If you first need a better understanding of what affects the underlying roofing price, see the North Alabama roofing prices guide.
Do You Have to Finance the Entire Roofing Project?
No. The full contract price and the amount that ultimately needs financing are not always the same number.
Some homeowners use a combination of available cash, legitimate insurance proceeds, and financing rather than borrowing the full project amount.
Using Cash for Part of the Project
If you have money available but do not want to use all of your savings, you may decide to pay part of the project directly and finance the remaining balance.
Reducing the amount borrowed can reduce both the monthly payment and the total finance charges.
Using Insurance When Covered Storm Damage Is Involved
If the roof has damage caused by an event covered under the homeowner’s policy, insurance may pay part of an eligible project. Coverage depends on the policy, cause of damage, roof condition, deductible, and the insurer’s claim decision.
If insurance pays part of the approved work, financing may be considered for a remaining homeowner responsibility, subject to lender approval.
Homeowners dealing with possible storm damage can review the site’s roof insurance information.
Comparing Financing With Paying Cash
Homeowners who already have enough cash for a roof still have a separate decision to make: use the cash now, finance the project, or use some combination of both.
That topic is covered separately in the finance versus cash roof guide, so this article does not duplicate that page’s primary search intent.
Make Sure You Need a Replacement Before Financing One
The financing decision should come after the roofing diagnosis.
If the damage is localized and the surrounding roofing system still has useful service life, a legitimate repair may solve the immediate problem for much less than a complete replacement.
Financing a full roof unnecessarily would mean borrowing money for work the property may not currently need.
The reverse can also be a problem. If the roof genuinely requires replacement, postponing the work solely because the lump-sum price is difficult can allow water intrusion or deterioration to affect decking, insulation, ceilings, or other parts of the house.
The best starting point is therefore an inspection and written scope of work.
If replacement is actually required, the roof replacement service page explains the replacement side of the project in more detail.
What Changes the Amount You May Need to Finance?
Two homeowners in Decatur or Athens can receive very different roofing quotes even when their homes appear similar from the street.
The project price can be affected by factors including:
- Total roof surface area
- Roof pitch
- Number of stories
- Accessibility
- Existing layers that must be removed
- Decking condition
- Flashing requirements
- Valleys and roof complexity
- Chimneys and other penetrations
- Material selection
- Waste and disposal requirements
- Whether eligible storm damage is covered by insurance
That is why homeowners should avoid planning around a generic online monthly-payment estimate before receiving a project-specific quote.
The most useful financing number is the payment for the roofing work your individual property actually needs.
How Do Credit and Lender Approval Affect Roof Financing?
Huntsville Roofing Solutions is not the lender. Financing is offered, when available, through third-party lenders.
Approval, available programs, rates, terms, and other conditions depend on the lender and the homeowner’s creditworthiness.
A $0-down option therefore does not mean that every applicant is automatically approved.
Homeowners concerned specifically about their credit profile should read the site’s dedicated roof financing with less-than-perfect credit in Alabama guide.
That page owns the credit-focused search intent, so this article intentionally does not attempt to duplicate it.
Questions to Ask Before Accepting a Financing Plan
- What amount am I actually financing?
- What interest rate or promotional terms apply?
- When does the first payment become due?
- Does interest accrue during any deferred-payment period?
- Is a promotional offer deferred interest?
- What happens if the promotional balance remains after the deadline?
- How many payments will I make?
- What is the total finance charge?
- What is the total amount I will repay?
- Can the balance be paid early without a penalty?
Where Should Decatur Homeowners Start?
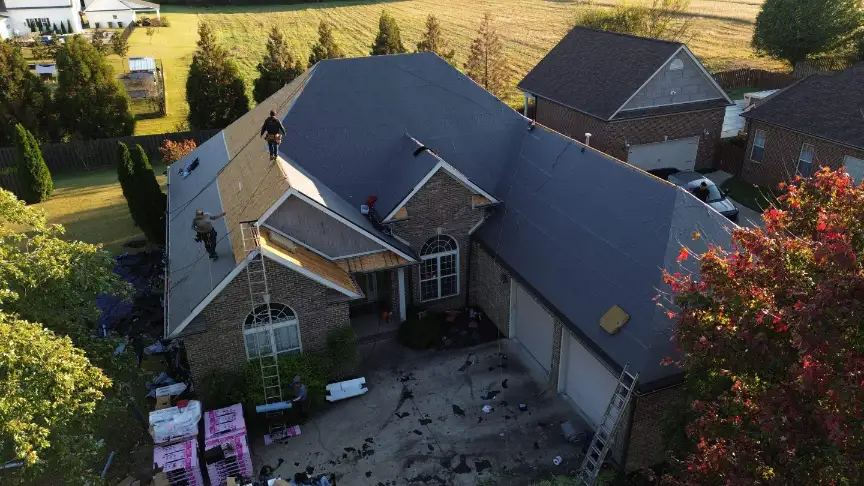
If your property is in Decatur, start with the Decatur roofing service-area page.
That page is the site’s primary local resource for roofing services in Decatur and should remain the destination for homeowners searching for a local roofer, repair service, replacement contractor, or storm-related roofing help.
After the roof has been inspected and the project amount is known, review the financing options for whatever portion of the project you do not intend to pay directly.
Where Should Athens Homeowners Start?
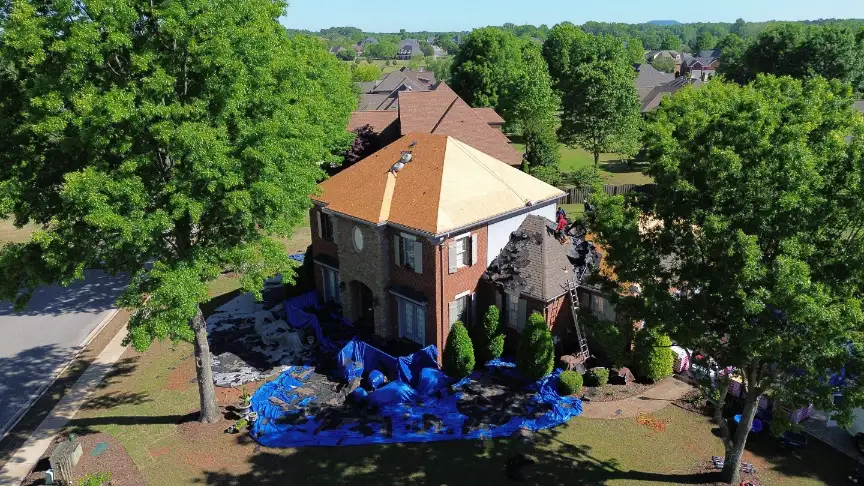
If the property is in Athens or the surrounding Limestone County area, begin with the Athens roofing service-area page.
That page remains the primary local landing page for Athens roofing services.
Once the roofing scope and written quote are established, compare the current payment options against the actual amount you need to finance.
A Practical Roof Payment-Plan Process
- Have the roof inspected. Determine whether repair or replacement is appropriate.
- Get the project price in writing. Do not build a financial plan around a generic roof-cost estimate.
- Check legitimate insurance coverage. If storm damage caused the problem, determine whether the loss may be covered under your policy.
- Calculate your actual out-of-pocket amount. Subtract any legitimate insurance proceeds and any amount you choose to pay directly.
- Determine how much you actually need to finance. It may be the entire project or only a remaining portion.
- Review the available lender options. Compare approval terms, rate, term, monthly payment, promotional conditions, and total repayment.
- Choose based on the complete offer. Do not select a financing plan only because it advertises the lowest monthly payment.
Frequently Asked Questions About Roof Payment Plans in Decatur and Athens
Are roof payment plans different in Decatur and Athens?
The site’s financing information applies across the broader North Alabama service territory, including Decatur and Athens. The important differences are usually the project amount, the amount financed, lender approval, approved terms, creditworthiness, and promotional conditions rather than the city itself.
Can I get a roof with $0 down?
$0-down financing structures are among the options described by Huntsville Roofing Solutions, subject to credit approval and current lender terms. A $0-down structure does not guarantee approval and does not automatically mean the loan has no interest or finance charges.
Can I combine homeowners insurance with roof financing?
When appropriate, insurance and financing can be used on the same project. If a covered claim pays part of an eligible roofing project, financing may be considered for a remaining homeowner balance, subject to lender approval.
Can I pay part of the roof in cash and finance the rest?
A homeowner may choose to pay part of the project directly and finance a smaller remaining balance. Borrowing less can reduce both the monthly payment and the total amount of interest paid.
Is deferred-interest financing the same as 0% interest?
Not necessarily. With deferred-interest financing, interest may accrue from the purchase date and be waived only if the full promotional balance is paid by the required deadline. If a balance remains after that deadline, accrued interest may become payable under the lender agreement.
Should I choose the financing option with the lowest monthly payment?
Not automatically. A low monthly payment can result from a longer repayment term. Compare the monthly payment with the number of payments, interest rate, finance charges, and total repayment before deciding.
What should I do first if I need a roof but cannot pay for it all at once?
Start with an inspection. Determine whether the roof needs repair or replacement and get the actual project price. Then check any legitimate insurance coverage, decide how much you want to pay directly, and compare financing for the remaining amount.
Get the Roof Price First, Then Compare the Payment Options
Whether your home is in Decatur or Athens, financing decisions are much easier when they are based on a real roofing inspection and written project amount.
Start by finding out what the roof actually needs. Then compare cash, eligible insurance proceeds, and current financing options for the remaining amount.
Request a free roof inspection and quote.
Review current roof financing and payment options.
Financing disclosure: Huntsville Roofing Solutions is not a lender. Financing is provided by third-party, unaffiliated lenders and is subject to credit approval. Rates, terms, promotional programs, and available financing can change. Other pages on this website have advertised both 120-month and 180-month repayment examples, but those references do not establish which plans, APRs, or promotional programs are currently approved for this business. Not all applicants will qualify. Promotional deferred-interest and deferred-payment plans may accrue interest and carry specific repayment conditions. Ask the lender for the currently available plan details, APR, any fees, the payment schedule, the total amount repayable, and the applicable promotional disclosures before making a borrowing decision.
Jordan is the founder and owner of Huntsville Roofing Solutions, a locally owned, fully licensed and insured roofing company serving Huntsville and North Alabama. He and roofing supervisor Barry Minor have handled residential and commercial roofs across the region — replacements, repairs, storm damage, and insurance claims — earning a 4.9-star Google rating along the way.