Roof Financing with Less-Than-Perfect Credit: What Alabama Homeowners Can Do
Can You Finance a Roof in Alabama with Less-Than-Perfect Credit?
If your credit is less than perfect, you may still have options for handling an urgent roof project in Alabama. Start by confirming whether you need a repair or full replacement, then get an exact quote before comparing payment choices. Check whether storm damage may qualify for insurance coverage, because reducing the amount you must pay can change the financing picture. If financing is needed, approval, rate, term, and available programs depend on the lender and your creditworthiness. Compare total cost, not just the monthly payment, and avoid assuming an advertised plan is guaranteed until you receive an actual approval.
Needing a roof at the wrong financial moment is frustrating, but a less-than-perfect credit history does not tell you what your actual options are until you know two other numbers: how much roofing work you really need and how much of that cost you actually need to finance.
That distinction matters. Financing a necessary repair is different from financing a complete replacement. An insurance payment can change the amount you need to borrow. A partial cash payment can change the financed balance. And the payment plan advertised on a website is not necessarily the plan or rate an individual applicant will receive.
The practical approach is to work through the problem in the right order rather than starting with your credit score.
1. Find Out How Much Roof You Actually Need to Finance
Before worrying about financing, make sure the project itself has been diagnosed correctly.
A homeowner who assumes a full replacement is necessary may be planning around a much larger expense than the roof actually requires. On the other hand, repeatedly repairing a roof that has reached the end of its useful life can mean spending money without solving the underlying problem.
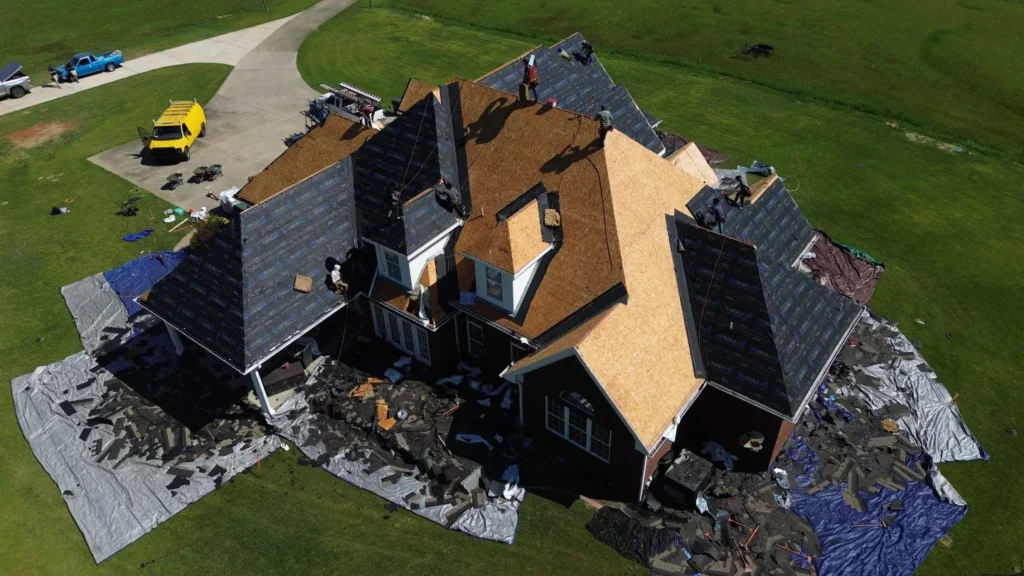
Start with an inspection and a written scope of work. You want to know whether you are dealing with:
- a localized repair;
- a larger repair involving decking or flashing;
- storm-related damage;
- or a full roof replacement.
If you are unsure which side of that line your roof falls on, use the roof repair or replacement decision guide before making a financing decision.
If a targeted roof repair can safely extend the life of the existing roof, the amount you need today may be substantially different from the cost of financing an entire replacement.
2. Get an Exact Roof Quote Before Shopping for a Monthly Payment
A monthly payment is only useful when it is connected to the actual amount your project will cost.
For example, an attractive payment shown for a sample project does not tell you what your own payment will be. Roof size, pitch, material, decking repairs, flashing details and project complexity can all change the amount that ultimately needs to be paid.
That is especially important when credit is a concern. Instead of asking, “Can I afford roof financing?” start with:
- What does my roof actually need?
- What is the written project price?
- Is another source paying part of that cost?
- How much would I actually need to finance?
- What terms am I actually approved for?
Working in that order prevents you from making a financial decision around an estimated payment for a project that may not match your home.
3. Check for Insurance-Covered Damage Before Financing the Entire Project
If the roof problem resulted from wind, hail, or another covered event, homeowners insurance may affect how much you ultimately need to pay yourself. Coverage depends on the cause of damage, your policy, the inspection findings and the insurer’s decision.
That makes insurance worth investigating before assuming the entire roof must be financed.
Suppose an inspection identifies legitimate storm damage and an approved claim pays part of the project. You may then need financing only for the remaining homeowner responsibility or other costs not covered by the claim rather than for the entire roof.
Financing and insurance therefore do not have to be either-or choices. They can sometimes be parts of the same payment strategy.
If your roof problem followed a storm, review the site’s roof insurance and claims information before deciding how much money you need to borrow.
4. Is There a Minimum Credit Score for Roof Financing?
There is no single minimum credit score published on this site that guarantees approval.
That is an important distinction because financing approval is more complicated than a headline score requirement. The financing programs offered through Huntsville Roofing Solutions are provided by third-party lenders, and approval, available terms, and rates depend on creditworthiness and the lender’s requirements.
In other words, do not automatically disqualify yourself because your credit is not where you would like it to be—but do not assume you will qualify for a particular advertised payment or promotional program either.
The useful number is the actual offer you receive after applying, not a hypothetical payment based on someone else’s credit profile.
5. Compare the Total Financing Offer, Not Just the Monthly Payment
When an applicant is focused on getting the monthly payment as low as possible, it is easy to overlook what creates that lower payment.
A longer repayment period can reduce the amount due each month, but stretching payments over more months can also increase the total amount paid when interest applies. A shorter term may require a larger monthly payment but reduce the amount of time interest has to accumulate.
When reviewing an approved financing option, look at the complete picture:
| What to compare | Why it matters |
|---|---|
| Amount financed | This is the portion of the roofing project being borrowed. |
| APR or applicable interest terms | This affects the cost of borrowing. |
| Monthly payment | This determines how the payment fits your monthly budget. |
| Number of payments | A longer term may lower the payment while extending repayment. |
| Total of payments | This shows more of the real long-term cost than the monthly figure alone. |
| Promotional conditions | Some promotions have specific deadlines or conditions that must be met. |
| Prepayment terms | Check your actual agreement before assuming how early payoff works. |
The site’s roof financing options provide the current plans and representative payment information. Use those figures as a starting point, then base your decision on the actual terms presented to you.
6. Consider Whether You Can Reduce the Amount Being Financed
If the financing terms on the full project are not comfortable, another question is whether the amount being borrowed can reasonably be reduced.
That can happen in several ways depending on the project:
- Insurance proceeds: If an approved covered claim pays part of the roof cost, financing may only be needed for the remaining amount.
- A partial cash payment: Some homeowners pay part of the project themselves and finance the balance rather than choosing all-cash or all-financing.
- A legitimate repair instead of premature replacement: If an inspection shows the roof still has useful life, repairing the actual defect may postpone the larger expense.
Reducing the amount borrowed does not guarantee a particular approval, payment, or interest rate. It simply changes the size of the financial problem you are trying to solve.
If you already have enough savings to consider paying for some or all of the project, the site’s finance-or-pay-cash roof guide covers that separate decision in more detail.
7. Be Careful With Promotional Financing Terms
Promotional plans can be useful when you qualify and understand exactly how they work. But the headline phrase—such as a promotional interest period—should never be the only part of the agreement you read.
The site’s current financing materials include promotional plans where the treatment of interest depends on paying the balance according to the promotion’s terms. That means homeowners should understand the deadline, required payments, and what happens if a balance remains after the promotional period.
This becomes even more important when you are uncertain what terms your credit profile will receive. Do not build your household budget around a promotional offer until you know that the lender has actually approved you for it.
For current plan details and disclosures, go directly to the roof financing page.
8. What If You Do Not Qualify for the Financing Plan You Wanted?
An approval that is different from the advertised example does not automatically tell you what to do next. Go back to the roofing problem and reconsider the variables you can actually control.
Ask:
- Does the roof require replacement immediately, or can a legitimate repair safely address the current problem?
- Is any of the damage potentially related to an insurable event?
- Can part of the project be paid from available funds while financing a smaller balance?
- Are the approved terms affordable when you look at both the monthly obligation and total cost?
- Would postponing the work allow the physical roof damage to become more expensive?
The right answer depends on the roof condition and the financing offer you actually receive. A contractor can explain roofing scope and price; the lender determines the financing approval and terms.
Should You Delay a Damaged Roof Because Your Credit Is Not Perfect?
Do not let uncertainty about financing become a substitute for finding out what is physically wrong with the roof.
A small repairable problem can sometimes become a larger project when repeated water intrusion reaches decking, insulation, ceilings or framing. At the same time, homeowners should not finance a full replacement simply because they are worried about a leak that could have been repaired.
The first action is therefore not borrowing money. It is diagnosis.
If the roof needs only localized work, repairing it may protect the home while avoiding an unnecessary replacement. If the roof genuinely needs replacement, you can then compare insurance, available cash and financing using a real project amount.
For homeowners who already know they need a complete roof, the roof replacement service page explains the replacement side of the project. For a broader overview of financing structures, see how to finance a new roof.
A Practical Order of Operations for Alabama Homeowners
If your roof needs attention and your credit history is making you hesitate, work through the situation in this order:
- Have the roof inspected. Determine whether the correct scope is repair or replacement.
- Get the actual project price. Do not plan around a generic roof-cost estimate.
- Check for legitimate storm-related insurance coverage. An approved claim may change the amount you need to fund yourself.
- Determine how much you actually need to finance. That may be the full project or only a portion.
- Review available financing. Approval and terms depend on the lender and creditworthiness.
- Compare the entire offer. Look beyond the monthly payment to the term, borrowing cost, total payments, and promotional conditions.
- Choose based on the roof and your actual numbers. Do not make the decision around an advertised example alone.
This sequence gives you something more useful than trying to guess approval from a credit score: a defined roofing problem, a defined cost, and an actual financing decision.
Frequently Asked Questions About Roof Financing and Credit
Can I get roof financing with bad credit?
Possibly, but approval cannot be guaranteed. Financing is provided by third-party lenders, and available plans, rates, and terms depend on creditworthiness and the lender’s requirements. The site does not publish one credit score that guarantees or automatically prevents approval.
What credit score do I need to finance a roof?
There is no single minimum score published by Huntsville Roofing Solutions for every financing option. Approval depends on the specific lender and plan. Rather than assuming you qualify or do not qualify based on a score alone, review the actual financing decision and terms offered to you.
Does $0-down roof financing mean everyone is approved?
No. “$0 down” describes the structure of an available financing option; it is not a guarantee of credit approval. Financing remains subject to lender approval and creditworthiness.
Can I use homeowners insurance and roof financing together?
Yes, they can be used together when appropriate. If an insurance claim covers part of an eligible roofing project, financing may be used for an remaining amount that the homeowner must pay, subject to financing approval.
Can I pay part of the roof in cash and finance the rest?
A partial-payment approach can be an option. Paying part yourself reduces the balance that must be financed, while financing the remainder spreads that portion over time. Review the actual financing agreement before deciding which combination works for your situation.
Should I finance a repair or a full roof replacement?
That decision should begin with the roof’s condition rather than the financing. If the damage is localized and the roof still has meaningful service life, a repair may be appropriate. If deterioration is widespread or the roof has reached the end of its useful life, replacement may make more sense. Have the roof inspected before deciding how much to finance.
Should I choose the financing option with the lowest monthly payment?
Not automatically. A lower monthly payment can come from spreading repayment across a longer period. Compare the amount financed, rate or interest terms, number of payments, total repayment amount, and any promotional conditions before choosing.
What should I do if I need a roof now but am worried about qualifying?
Start with the roof rather than the loan. Get an inspection and exact quote, check whether legitimate storm damage may involve insurance, determine the amount you actually need to fund, and then review the financing options available to you. That gives you real numbers instead of guessing from your credit history.
Find Out What Your Actual Roof Financing Options Look Like
Less-than-perfect credit should not force you to guess about either your roof or your payment options. First determine what work the home actually needs. Then compare financing based on the real project cost and the terms for which you are actually approved.
See the current roof financing options available through Huntsville Roofing Solutions, including current program information and financing disclosures.
Financing is subject to credit approval and is provided by third-party, unaffiliated lenders. Huntsville Roofing Solutions is not a lender. Rates, terms, monthly payments, promotional programs, and availability depend on the lender, amount financed, approved credit terms, and other applicable requirements. Not all applicants will qualify. Review the financing agreement and disclosures before accepting an offer.
Jordan is the founder and owner of Huntsville Roofing Solutions, a locally owned, fully licensed and insured roofing company serving Huntsville and North Alabama. He and roofing supervisor Barry Minor have handled residential and commercial roofs across the region — replacements, repairs, storm damage, and insurance claims — earning a 4.9-star Google rating along the way.