Summary: An 18-month deferred-interest roof financing promotion, when available to an approved borrower, may allow a homeowner to replace a roof without paying interest on the financed amount if the promotional balance is paid in full by the specified deadline and all other agreement conditions are met. Deferred interest is not the same as a true 0% APR loan: interest may accrue during the promotional period and become payable if the payoff conditions are not satisfied. A $0-down option, if offered, also requires lender approval. These programs may be useful for homeowners expecting a tax refund, work bonus, or insurance payment, but the exact rates, deadlines, fees, and eligibility requirements must be confirmed in the current financing agreement.
Understanding Deferred Interest Roof Financing
When searching for ways to afford a sudden roof replacement, homeowners often look for offers described as “0% interest” or “no interest if paid in full.” These phrases can describe different types of financing. A true 0% APR promotional period generally does not accrue interest during that period. A deferred-interest promotion may accrue interest in the background, then waive that interest if the promotional balance is paid in full by the required deadline and the customer follows the agreement’s other terms.
The distinction matters because an unpaid promotional balance may trigger previously accrued interest. The Consumer Financial Protection Bureau explains how deferred-interest promotions work and why making only minimum payments may not be enough to avoid interest charges. The precise rules for any roof financing offer depend on the applicable lender contract.
To help you evaluate your roof financing options, we have broken down deferred interest into four areas: how it works, how to plan your payments, the risks, and who might benefit.
Vector 1: The Mechanics of “Deferred” vs. “Waived”
One common misunderstanding about deferred-interest financing is assuming the interest rate itself is 0% throughout the promotional period. Under a typical deferred-interest arrangement, interest can accrue on the outstanding balance at the rate stated in the financing agreement, even though the lender does not immediately require payment of that interest.
If the promotional balance is paid in full by the deadline and the other conditions are satisfied, the accrued promotional interest is waived under the offer’s terms. If the balance is not paid off in time, some or all of that previously accrued interest may be charged. Do not assume a particular interest rate or promotion start date; confirm both in your signed contract or promotional addendum.
Service Finance explains that, for its promotional installment loans, the offer’s specific conditions are shown in the retail installment contract or an attached addendum. See the Service Finance frequently asked questions for guidance on where to find those terms.
Vector 2: The Real-World Math on a Huntsville Roof
Let’s consider an illustrative Huntsville roof replacement with a $15,000 financed balance. These calculations assume no additional financed fees or charges and do not represent a quoted loan offer.
- Relying Only on the Minimum Payment: A lender may require periodic minimum payments, but those payments may not be enough to pay the promotional balance in full before the deadline. Review the actual billing schedule rather than assuming the minimum payment will satisfy the promotional payoff requirement.
- Planning to Pay in Full: Dividing $15,000 by 18 months gives approximately $833.33 per month. For an additional timing cushion, budgeting approximately $883 per month over 17 months would repay $15,000 before the end of an 18-month period, assuming each payment is made and credited as planned and no extra charges apply. Confirm the lender’s exact promotional expiration date, payment-crediting rules, and payoff amount before relying on either example.
The safest approach is to request a written payoff figure and aim to clear the entire promotional balance before its expiration date, rather than scheduling your final payment on the last possible day.
Vector 3: The Retroactive Catch (What Happens When the Promotion Ends?)
A deferred-interest promotion can become much more expensive if its payoff conditions are not met. For example, if an agreement requires full repayment within 18 months and a balance remains when that period expires, the lender may assess interest that accrued during the promotional period. This can be substantially more than the interest on the small remaining principal balance alone.
The charges are governed by the contract’s stated interest rate, accrual method, due dates, and other terms. Missing required payments may also affect promotional eligibility or lead to late fees. The exact consequence is not determined simply by reaching “month 19”; it depends on the specified promotional expiration date and the lender’s agreement.
Before accepting an offer, ask the lender to explain what happens if even a small balance is still unpaid at expiration, whether late payments affect the promotion, and how accrued interest is calculated.
Vector 4: Is an 18-Month Deferred Interest Plan Right for You?
An 18-month deferred-interest roof financing promotion may suit homeowners who have a realistic, documented plan to repay the balance within the promotional period. Consider these examples:
- The Bridge Funder: You reasonably expect an insurance payment, work bonus, tax refund, or other funds before the deadline. Because those funds can be delayed or smaller than expected, keep an alternative repayment plan.
- The Aggressive Saver: You have enough reliable monthly cash flow to pay more than the required minimum and clear the promotional balance early without exhausting emergency savings.
- The Home Seller: You plan to sell the home and use some of the proceeds to repay the financing. Confirm that the payoff will be possible at closing and that your sale timeline leaves enough room before the promotional deadline.
If you prefer smaller scheduled monthly payments and do not expect to repay the balance quickly, a fixed-rate installment loan may be more suitable. Our published financing information has referenced both 120-month (10-year) and 180-month (15-year) repayment options, but their current availability, APRs, and eligibility criteria must be confirmed with the financing provider. Longer repayment terms may reduce monthly payments while increasing total interest costs.
Take Control of Your Roof Project
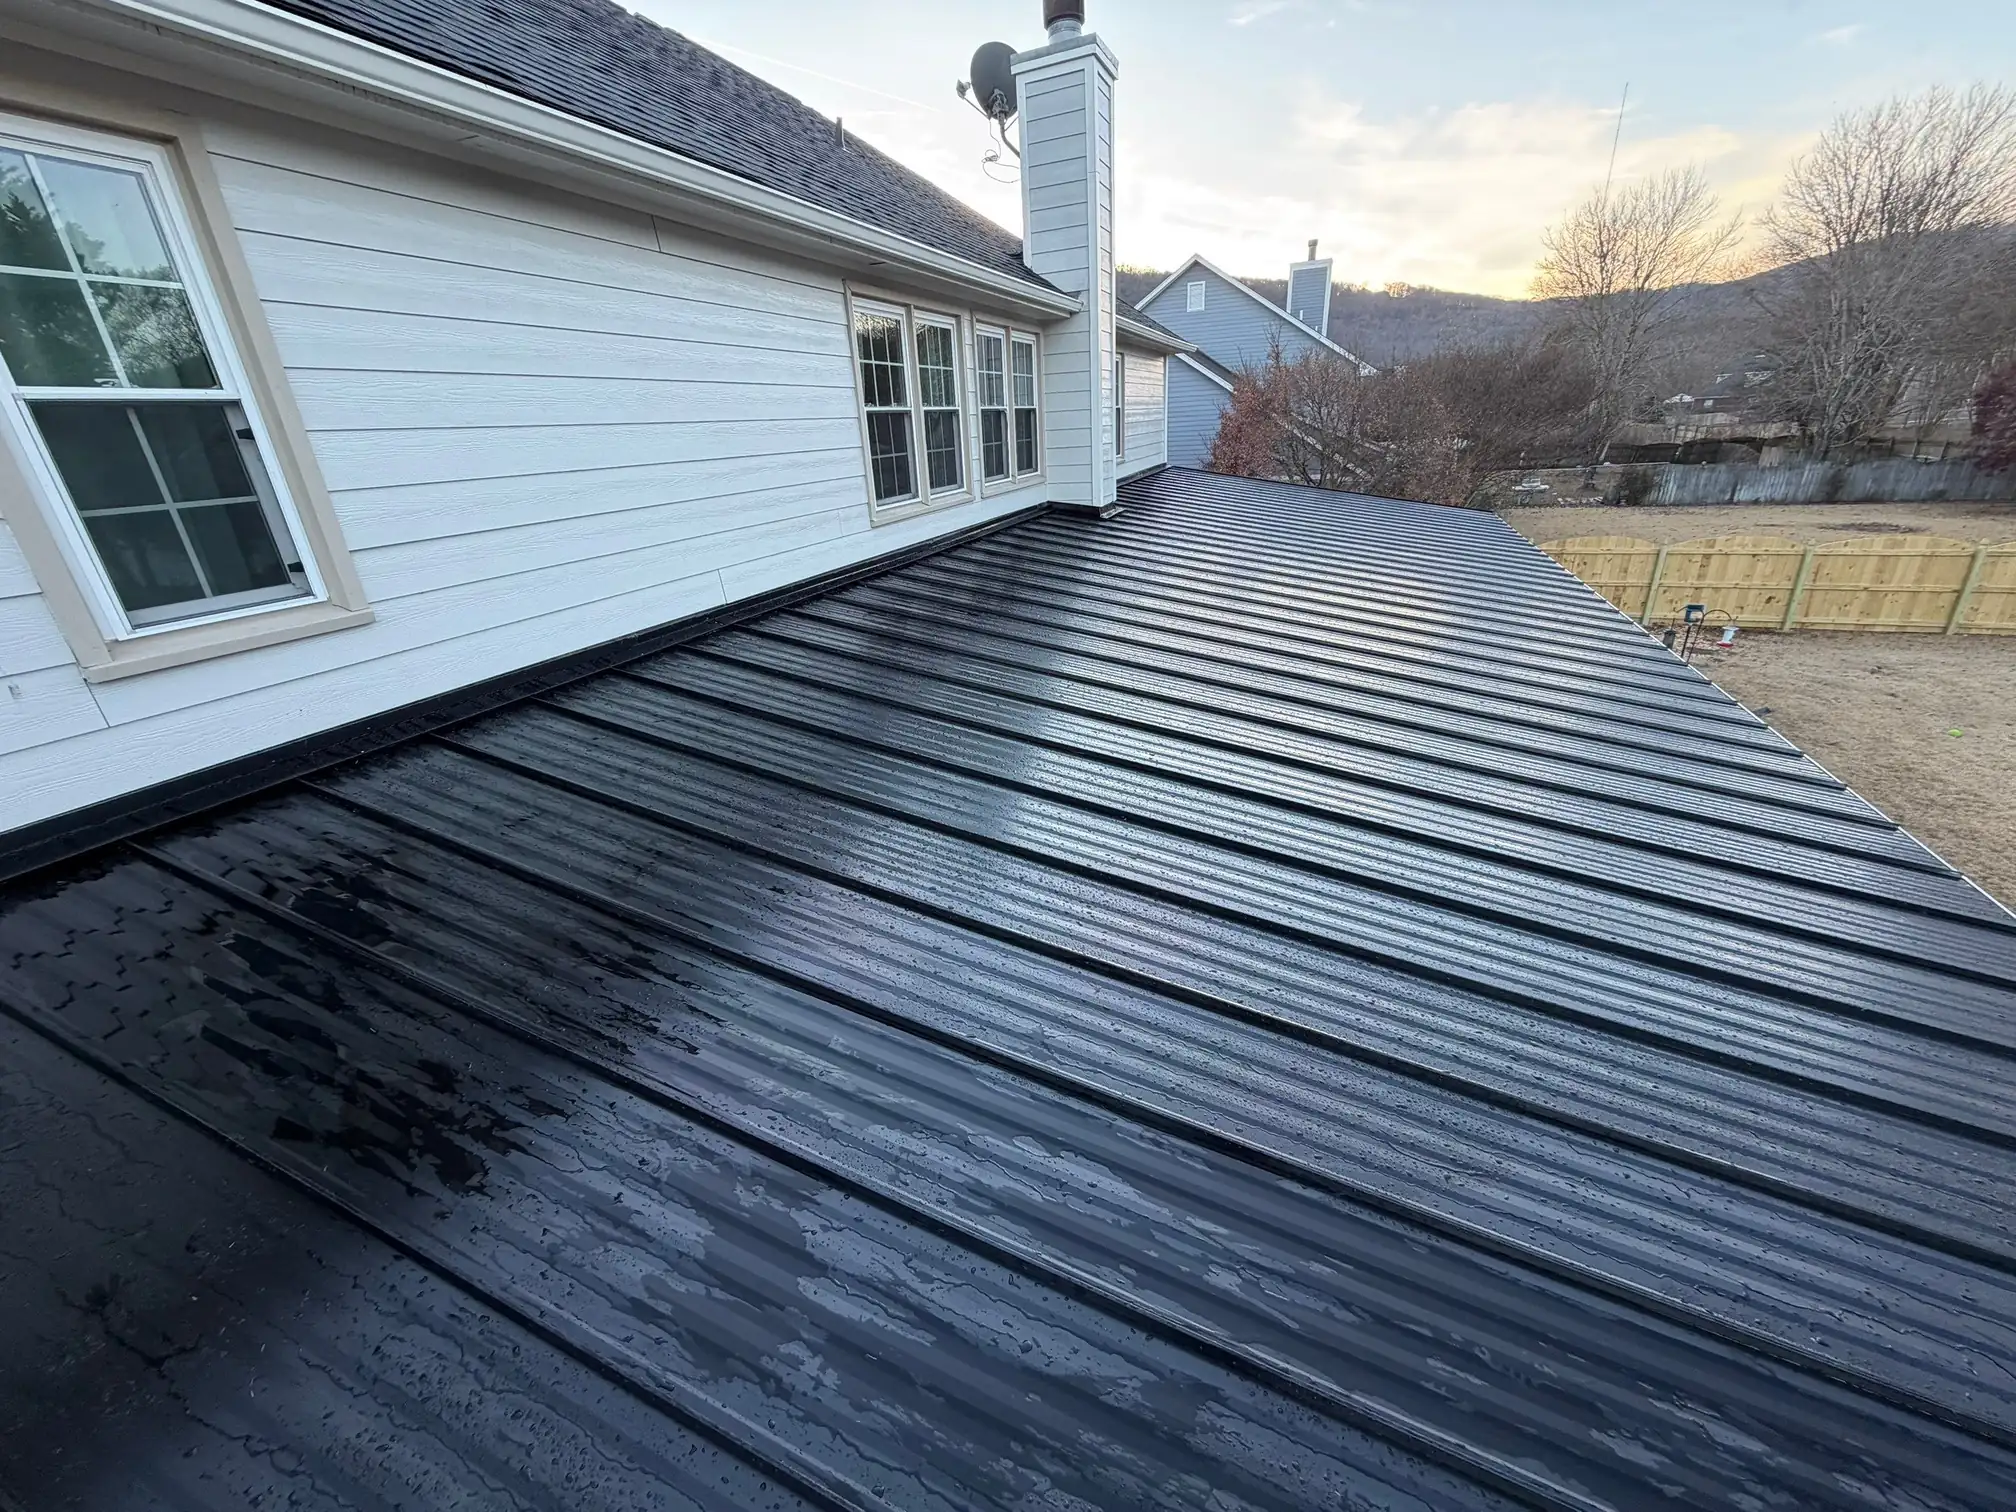
A new roof is a major investment, but you may have financing choices that help spread the expense. At Huntsville Roofing Solutions, we can discuss potential deferred-interest promotions and longer-term installment financing so you can compare the monthly payments, total repayment cost, and risks before applying.
Financing disclosures: All financing is subject to credit approval and the lender’s current programs. Promotional availability, down-payment requirements, interest rates, fees, repayment schedules, and waiver conditions vary by offer. The signed loan agreement and any promotional addendum control. Visit our roof financing page or contact us for a roofing estimate to learn about the options currently offered.
Jordan is the founder and owner of Huntsville Roofing Solutions, a locally owned, fully licensed and insured roofing company serving Huntsville and North Alabama. He and roofing supervisor Barry Minor have handled residential and commercial roofs across the region — replacements, repairs, storm damage, and insurance claims — earning a 4.9-star Google rating along the way.